Kevin Kim, Esq.:
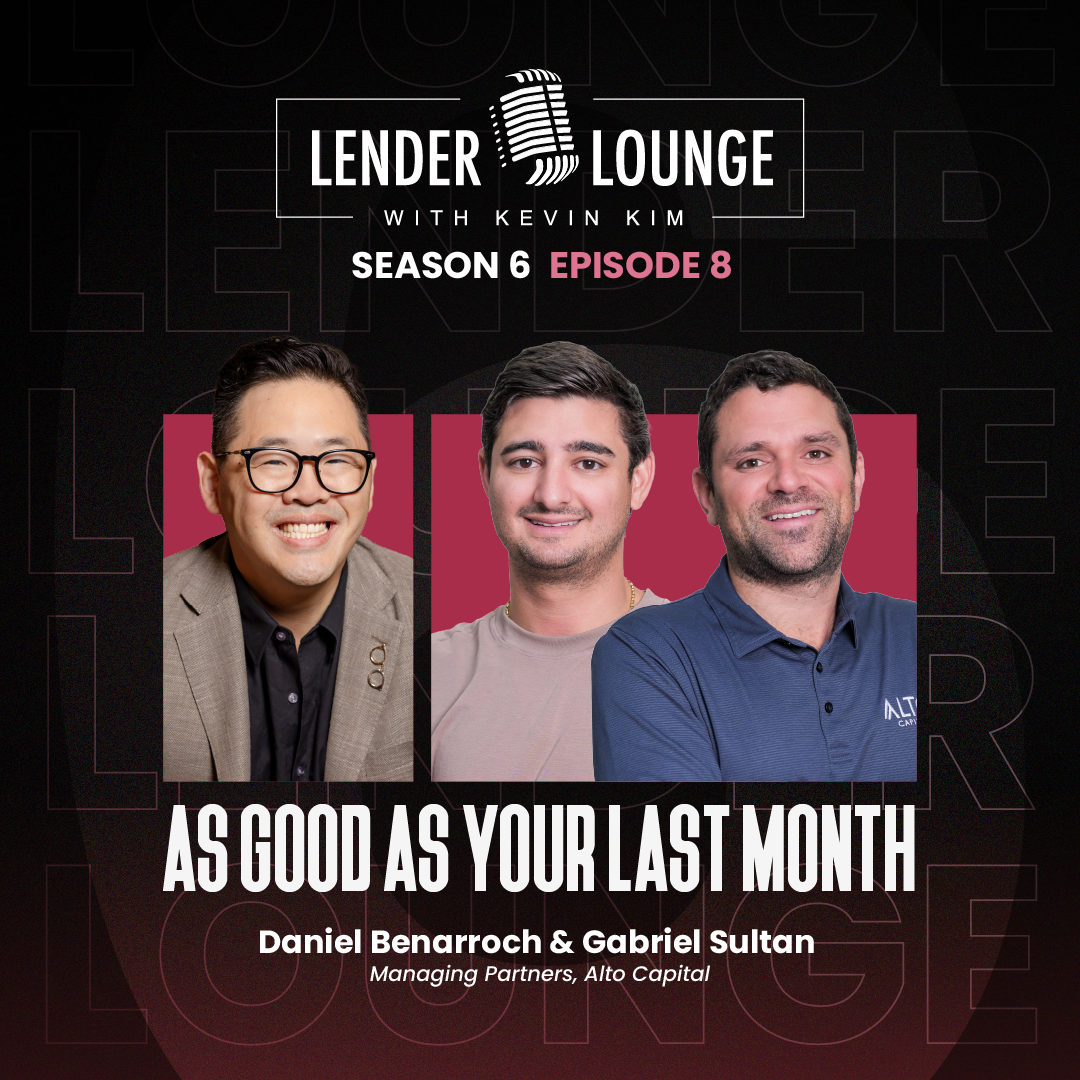
You’re listening to Lender Lounge with Kevin Kim, a podcast dedicated to helping our listeners in the private lending industry grow, improve, and streamline their business. I’m Kevin Kim, Partner at Fortra Law, the nation’s largest private lending law firm. Join me as we chat with the best and brightest in private lending.
They’re eager to share their years of wisdom and best practices for lenders, brokers, borrowers, investors, and more. Subscribe to Lender Lounge on your favorite podcast platform and visit our website, Fortrellaw.com, to learn more about how we can help you scale. Check out the episode summary below for other valuable resources.
Hey, guys. Kevin Kim here, coming to you on location for another episode of Lender Lounge with yours truly, Kevin Kim. Today, we have our special guests.
They flew in all the way from Miami just to do this episode with us and also to attend our conference. So, you know what, why don’t you guys introduce yourselves to our audience and if we can get started from there?
Gabriel Sultan:
So my name is Gabriel Sultan, born and raised in Venezuela, country in Latin America for anybody that doesn’t know. I moved to a United States in 2009, and then I’ve been in Miami ever since. I started in the lending world back in around 2017 as an investor.
Then I’ve known Daniel since high school. We both went to the same high school and middle school in Venezuela. So we are buddies since we were 10 plus years old.
And then I don’t know if you want to tell the rest of the story of how we started or not.
Daniel Benarroch:
Yeah. So my name is Daniel Benarroch, a very similar background to Gabriel, which I think it’s important for a partnership down the road. Also born and raised in crack as well, I move a little bit later in 2012.
Here to Miami, I actually finished my college and my master’s in Florida, and I actually started getting my first touch with like hard money or private lending back then. I’ll say around 2014. OK, so right away.
Yeah, my father-in-law actually had a realtor that reached out and said, look, there’s an opportunity to lend money to international people here that, you know, they cannot get access to like institutions or like financing. Will you be willing to lend money? And he said, yes, and pretty much me and my wife now.
We’re pretty much servicing those loans on a small excel. And we were obviously, you know, speaking with attorneys, trying to get payoffs. But you know, back then it was something I never in my mind imagined that I will end up doing this for the rest of my life.
Kevin Kim, Esq.:
So the business started in your garage.
Daniel Benarroch:
Pretty much. I think I had a pretty early interaction. But back then it was like the Wild West, you know, you only asked for like a passport and a visa and an address.
Obviously the industry has changed and the institutions has come in. So it’s a whole different business right now. But I think, you know, the base of that, it was something I touched really early back on 2014 when I started doing those small servicing.
Kevin Kim, Esq.:
And so for our audience, the names may not be familiar with the company, probably is currently you guys called Auto Capital based out of Miami. They’re like, I think you guys are the number one shop in Florida, right? So number one RTL producer in Florida according to Elementix and Forecasa and all those new data companies, you guys were called something else before.
Gabriel Sultan:
When we started, we started by equity lending solutions. So just, you know, a bit of back story. So I started investing with Daniel.
He was working for another gentleman through another company.
Kevin Kim, Esq.:
And because you were a partner with somebody else back then.
Daniel Benarroch:
Yeah. Yeah. Yeah.
So pretty much on 2014, obviously I was doing this as a just helping my loss. Manage that small portfolio. Actually, after I graduated, I went for my real estate license as a sales associate, as they call it.
And obviously I started to get more interesting into the real estate world. Obviously I knew realtors, lenders, you know, the whole 90 yards that you need to be a realtor. But I didn’t like the business.
You know, I didn’t like selling or, you know, being fake to people about. Yeah. You know, yeah.
When you show a house that, you know, phases as well, you say it’s a beautiful sunrise. And when you don’t want that people to buy the house, you say, you know, sunset is the best because I didn’t like that type of, of, of interaction. So I actually went to another venture with a, with a FedEx ground business.
I own a FedEx trucking business and actually invited Gabriel and he bought one of those routes. So we, we’ve been bought a route.
Gabriel Sultan:
Yeah. And like our first business, other than friendship business was in the trucking business. And I think right now we’re not investing in anything that has wheels.
Daniel Benarroch:
Yeah.
Gabriel Sultan:
Nothing that has wheels we don’t touch. We learned our lesson.
Daniel Benarroch:
Yeah. So after we sold that business, I think that was early 2016. I had a friend that was starting a fund for like private lending.
And he called me and said, like, I think, you know, a little bit about these come here and help me. And I started pretty much raising money for him. So they were pretty much closing balance sheet loans and they’re all located in date with private investors.
So obviously Gabriel was one of those investors where I played one of those ones.
Kevin Kim, Esq.:
So that’s how it connected. And you were at a different shop. You were investing.
Gabriel Sultan:
Yeah. And then he pretty much said, Hey, why we don’t do it together? And by coincidence, I just had landed back from a trip to LA.
And a body of mine was showing me on his phone, like, look, this is this thing that’s called peer street. This is like 2017, 2018. And look at this thing.
This is PeerStreet and you can invest $10,000 into whatever and make 10%. And when I go back to Miami, he’s telling me, look, partner with me. And I’m like, Daniel, you don’t need a hundred million to lend the hundred million.
Like let’s partner up together and let me run capital. Let me find capital, like institutional capital. And, you know, we don’t need a hundred million to lend a hundred million.
I think with the balance sheet that we had from friends and family, whatever, we could, you know, make some damage. And that’s pretty much how we started in mid to late 2019. But we were only lending to our core product back then.
There was pretty much foreign nationals coming to South Florida. And buying or refinancing or selling or whatever they wanted to do with their investment property, they couldn’t access local banking because they didn’t have US income and banks didn’t even want to touch them back then.
Kevin Kim, Esq.:
It was like a very niche product that many shops here were struggling with.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
And out there, we knew that that was mostly driven by the local community.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
Right.
Daniel Benarroch:
And but then so that was all you have to remember back then, there was a lot of new developments closing. So we had all of those buildings. You know, there were 500, 400 units where a lot of those buyers were foreign nationals.
They had a 40% down three, four years earlier. And now they have to close some of them didn’t have the financial capabilities to close. And some of them wanted some kind of financing in order to close those units.
So I, you know, we were at the right time of the perfect storm, how we call it. So we started doing a lot of those closings for those development buildings that were.
Gabriel Sultan:
So I was pretty much, I guess, our first year. It was all like foreign national investment properties. And I would say, you know, by 2020 would say, OK, we want more.
We want to grow. How do we grow? And people started saying, Hey, the fix and flip value add ground up.
And in all honesty, we didn’t know what we were doing. I think the first fix and flip that we finance was in Tampa and he would when you went to North Florida. Yeah, I don’t know why we met our developer or entrepreneur in Tampa.
So he was like, Oh, I’m doing a flip. I’m out of a share. We’ll do it.
I guess the appraisal didn’t even have a RV. Like, in all honesty, we didn’t know what we were doing.
Kevin Kim, Esq.:
I mean, if he was 17, probably no praise. Oh, 2020. Yeah.
We were doing drawers, 20, 20 years.
Gabriel Sultan:
Yeah, but the drugs, we were advancing them. We were like, Oh, I want to do this. So we would give them the money.
Kevin Kim, Esq.:
And then we call those country club deals.
Gabriel Sultan:
Exactly.
Kevin Kim, Esq.:
I’ll go and figure it out. You have to go out somewhere, right? And that’s the beauty of our industry.
There’s a room for everybody.
Gabriel Sultan:
He was handling a client that’s still our client. It’s probably one of our biggest clients currently. And he got married in 2021.
So when he gets married, he goes on his honeymoon. So I take over his whole workload, right? For the three weeks or whatever.
So going into a thing and back then we were already selling loans. So I started doing the calculations and I’m like, this doesn’t add up. There has to be a mistake.
This is like 120 LDC loan. And I’m like, what’s, what am I doing wrong? And I didn’t want to bother him.
He’s traveling, right? Cause we were doing another deal for the same guy. And he’s like, Daniel was giving me eggs.
Why are you charting it in half? Oh, yeah, he was like, and then I called him. I’m like, look, I know you’re like in Hawaii or in Fiji.
Daniel Benarroch:
Yeah, yeah, yeah, yeah.
Gabriel Sultan:
Fuck did you do? You’re giving this guy more money than his costs, right? That’s how we started, like, on the ballot.
Daniel Benarroch:
Was that loan on the books or that loan? Yeah, well, I mean, our business has always been to fund deals with our own pool of money and then we balance it for a couple of days. And maybe we put it in our line of credit.
We have a balance sheet vehicle now, but, you know, the majority of our production, it’s being sold, obviously on the secondary market.
Kevin Kim, Esq.:
Quite the evolution then. Cause from, I was a garage, we call it garage band fund. And in the fund world is like, you’ve got a garage band fund, which is like two guys in the laptop just trying to make ends meet and figure it out.
And basically similar story and you’re just, and you’re like trying to figure out underwriting and find borrowers. So like, this is, you’re still ELS at the time. Yeah.
Gabriel Sultan:
Correct. Yeah. We’ll see what equity landing and all until December 31st, 2024.
Kevin Kim, Esq.:
Okay. So recently, yeah, the name Alto has been, okay, it’s a rebrand in 2024. Okay.
But this is one of the interesting things about what you just said is you started the business with the intention that you’re going to work with the secondary market, right? So to me, that’s like the right now in today’s market, it’s kind of the, the, what I would say the trend is when most folks starting out are starting out thinking, kind of like a mortgage banking model, right? We’re going to, you know, correspond, table, fund, sell.
We’re not going to, we make people a little bit on our own, what we have, but that’s as far as it’s going to go. You were unique at the time. I mean, even in the Florida market, by that point in time, we had enough representation in Florida to know that was not the main stream model in Florida.
Gabriel Sultan:
Yeah. Look, if we liked the deal, we would do it. It didn’t matter if we had capital for that deal.
We would just keep it on the balance sheet and.
Kevin Kim, Esq.:
So you would keep, you know, you have enough balance sheet.
Gabriel Sultan:
Yeah. Yeah. And if we liked the deal, we knew that at some point we were going to be able to convince an institution, an investor to do the deal.
For example, we did a $4 million loan on a $14 million farm in no California, like on a question farm, right? But, you know, we’re lending $4 million against 14. At that time, nobody wanted to charge agriculture a property, but it made a ton of sense.
And it was on their contract. It was going to be sold in like 120 or 180 days. So we did it.
Kevin Kim, Esq.:
And you’ve always kept room for the discretionary, possible stuff.
Gabriel Sultan:
And I think that’s one of our key things that our borrowers, our partners, you know, referral sources, they know they can trust us. And we’re not just like the cookie cutter lender. We’re only going to do down the fairway deals.
Like, again, we’re not going to do hairy deals. But if it makes sense, we’re going to do it or we’re going to try to do it. Like we don’t do commercial.
We’ve done commercial. But if you call me to a hey, Gabriel, I have, I’m giving you an example. There’s a marina in Florida.
It’s worth $10 million and they want $2 million. Chances are is that we’re going to do it. So yeah, I think that, you know, when we, when we were scaling, that’s one of the key factors that differentiated us from our peers in Florida, cause, especially in Florida, there’s a big group of referral sources, attorneys, real tourists, CPAs, you have less restrictions than we do here in California.
Yes, exactly. We’re not going to call it the Y, Y, West, but I mean, we’re, we’re proud of being Floridians and we’re happy with our state and with everything that’s going on. But all of those people, when you tell them, no, they just turn to the other guy.
And that guy starts saying, yes, they’ll give them everything. They’ll give them the good, the bad, and they’re not so bad. Right.
So we always try to tell them, hey, this is our down the fairway. This is what we want. But if it makes sense, if you would put your money into it, chances are is that we would do it.
Kevin Kim, Esq.:
That’s interesting because Florida for the longest time had this weird reputation of like super, super institutional shops. And then you had the vast majority of lenders, especially in our industry, where what we would call country club guys. The hairy, you know, there’s no appraisal, no FICO.
Kind of just look at the deal and make sense. They just do it. Right.
And that was the vast majority of the floor market. When did you guys start seeing your market become much more formalized and like, okay, now the market is really starting to solidify around a real practice.
Daniel Benarroch:
I mean, they still they’re, they’re super important shops in Florida. But, you know, obviously this is their primary business and they have an enormous amount of power, you know, balance sheets, north of $500 million. And they obviously were taking the majority of the loans.
But when we came into play, you know, we started doing the smaller loans at cheaper rates, institutional capital started flowing. So we started taking some of those business from them. And then, you know, back then, I think we used to cap our maximum loan amount at 1.5 million if that not mistaken. So we started pushing for, hey, we need, you know, bigger loan amounts. You know, we’re competing on this market. Let us go to two or three, four million dollars.
Kevin Kim, Esq.:
Yeah.
Daniel Benarroch:
So obviously we were pushing those limits, hires and hires. And we’re taking that market share from them. Now, obviously there are transitioning into a different kind of assets.
You know, they were doing like condo financing for like a special assessment with where the condominiums in it. The HOA needs like a special financing. Maybe land deals that still don’t have the capacity or small capacity for those or like super big deals that we’re, you know, I think we’re starting to be able to touch those, but anything like not of 20, 30 million dollars, which is, you know, they’re playing around right now.
Gabriel Sultan:
Yeah, I think the big balance sheet lenders in our market, with all the institutional capital flowing in, we are way cheaper than them and faster. So they are just turning into CRE shops. Five, seven years ago, RTO was not a thing.
It was just hard money, right? In the Florida market, it was hard money lending. You know, it didn’t matter what.
If you were charging 10, 12, 13%, it’s hard money. And you know, the last three, four years now, okay, you have RTO, you have hard money, and there’s a difference between both, right?
Daniel Benarroch:
We actually did a lot of like education on our market because, you know, realtors, brokers, wholesalers, they were all coming to us. They said, look, you know, we need this deal done. And we will go and say, look, the guy, it’s a 580 credit score.
He won’t qualify and was like, but this is hard money, you know, what are you looking at? Credit, you only look at the assets.
Kevin Kim, Esq.:
You mentioned that. And that’s the same story you saw here in California, Arizona, but it’s way earlier, right? We had, we were, this market was hard money until roughly 2014.
And then the RTL product came in 2014 to 2016, formalized around industry standards and ever since never looked back, right? And you still have, like, that’s the middle of the fairway. And then you have the rest of the whole, and that’s where the fringes play, but it’s a large fringe, right?
So like, that’s a very, as fascinating that that only evolved within the past 10 years. A lot of folks who are in your shoes, make that choice. And we’re going to play with the secondary market.
We’re going to interact and sell loans. We’re going to do that. The majority of people who start out like that are either one of two things.
They’re either like basically brokers who table fund correspond, they’re that camp or they come from that world, right? They have a capital markets background and they’re focused on really running a mortgage banking shop. But this is not, you know, kind of a mixed strategy.
And it was literally just, hey, piercing the thing, we don’t have to do it by ourselves. But that really it, I think.
Gabriel Sultan:
That was really it. We were impressed that people were buying this sort of credit risk. And that’s where we said, oh, we don’t need $100 million to lend $100 million, you know?
If we have 10, I think we could do it. So that’s how it started evolving. And we’re super happy with our growth.
As you said, I think, I don’t think this year we’re number one in Florida by far. We’ve gone over a billion dollars this year.
Kevin Kim, Esq.:
Well, you guys have weathered the storm better than it most. I mean, everyone is talking about how tough it is in Florida.
Gabriel Sultan:
Yeah. Yeah.
Kevin Kim, Esq.:
But your guys’ volumes don’t speak to that.
Gabriel Sultan:
Well, again, we’re growing. We’re growing. We have an office right now in Austin.
We’re trying to open offices in the Carolinas. And we’re getting volume and flow from, you know, Tennessee, Georgia and the southeast. But again, yeah, Florida right now, there’s markets within the Florida markets.
There’s some markets, right? The Gulf Coast of Florida, everything north of Naples, south of Tampa. We don’t touch.
We did a lot of it in 2020, 2023. And unfortunately, performance was not there. So we passed lending there for the last, I guess, 1824 months.
Kevin Kim, Esq.:
So are the most of the market?
Gabriel Sultan:
Yeah.
Daniel Benarroch:
And we call it pretty early. I mean, we knew that something was not going on because we had a lot of exposure. Is a smart app and 23 said?
Gabriel Sultan:
Yeah. Much earlier. Yeah.
Kevin Kim, Esq.:
Most of the market turned it off last year. Yeah.
Gabriel Sultan:
I mean, because we did a lot. So we had all the data.
Kevin Kim, Esq.:
Yeah, it was huge. And you’re on the ground. You’re right there.
Gabriel Sultan:
Yeah. We’re there. We were seeing, you could just drive there.
Look, the first time I went there to inspect properties, it’s the main town over there is called Lehigh Acres. And I went with a client, he was showing me properties. I went out of the property and I called him and I was like, I don’t know who would look here.
It’s horrible. So when I said that, I’m like, we shouldn’t be lending here. You know, I don’t like it.
Although there’s a lot of people building there, buying there, nothing against it. But in my personal take is I wouldn’t live there.
Daniel Benarroch:
People that move there from Miami and the main city is looking for affordability. They went there. They were able to buy a house for 300, 400,000 max at a time.
But then a few years later, there’s no opportunities here. We still have to drive and commute to Miami.
Kevin Kim, Esq.:
What’s in the office now?
Daniel Benarroch:
So what do we do here? You know, and part of it, obviously, Lenard and the big developers came in and they were selling at 250 when our borrower calls was 300. So obviously they were out market pretty quick.
And then obviously inventory started skyrocketing.
Kevin Kim, Esq.:
You guys’ growth patterns are so different than anyone we’ve had on the show. And I love it because one of the core messages that the show is trying to tell everyone is there’s no right or wrong way to do this, right? But there’s usually a common thread with our guests about, there’s a moment, right?
When you’re now you’re organized, you’re ELS, you’re really trying to storm those beaches and really grow the business. And there’s like some moment where like, okay, now we’ve got this. Like we’re cooking with gas now.
Like we’re a real company. We’ve got recognition. You know, this is really going to work.
This has got scale to it. When was that for you guys? Is that a moment or a deal or like a capital partner placement or something like that?
Okay, now we’ve got this.
Gabriel Sultan:
I mean, I don’t think it’s a moment per se, like something I click is, I think it’s along the way, you start feeling recognized when you go to banks, when you go to hedge funds, when you go to capital partners, I say, oh, we know who you are. We know what you’ve thought and we’ve seen your performance and we want you. We want to partner with you.
We want to do business with you. And that’s when everything starts, you know, making sense. Hey, everything’s paying off what I’ve been doing.
But in all honesty, I think we still have a lot of runway to go. So I’m more on the side of not pessimistic, but I’m always trying to grow and do more things. So I think there’s still a lot of runway there, right?
I think our goal is to be, you know, top 10 in the next 24 months, right now in volume, I think we’re 15, so we’re about there.
Daniel Benarroch:
And you’re a regional shop. So it’s like, not only that, but I show him last time. The last time we checked, like, Forecasa and Elementix for like the top 10, top 15, I told you, look, I think we’re one of the only ones here that’s still not like financially backup or we sold to like a big institution.
There’s not many here. I mean, the top 10, the answer would be, yeah, I mean, probably like the first top 10 were already, you know, shops that sold.
Kevin Kim, Esq.:
Of the top 10, the ones that are independent technically, there’s only about 5% of a few of them are like RCN is up there. RCN is technically still independent, right? They’re not owned by anybody, by any institution per se.
But then once you get down from 10 to 20, there’s a lot of like, you know, independent shops, which has been around for 15, 20 years.
Gabriel Sultan:
Yeah, that’s true.
Kevin Kim, Esq.:
Yeah. That’s a great, I mean, I like that. Basically, you’re telling us you haven’t made it yet.
Like it, you keep it humble. Yeah, my opinion, because you’re in the top 20, right? And that’s no joke because you’re regional.
It’s not, it’s easy, it’s easier to do it when you have this massive machine and you can go out and just pump volume by just crazy brokerage and do all that. When you’re keeping it regional, that means that you’re, you’re not, you’re concentrating in that kind of like, I guess it’s called southeastern quadrant of the country and you’re still pumping the volume. And you’re also not suffering from, can we talk about this offline?
Like you guys aren’t facing the same headwinds a lot your colleagues are.
Daniel Benarroch:
Yeah, and I think this is a, we might spill a little bit of our secret sauce here, but I think our success has been because we have, keeping that like, our ownership and our management, it’s very tight. We, we still go into the need and grades, you know, we still get involved into underwriting issues, servicing issues. You know, if we have a call from an investor, look, what’s going on with the payment from this board, where, and it was my board, where I’ll be the one calling him and say, look, you know, we have to figure out something.
And I like first time I played golf with these boys in their hometown, they were working at the time. And we actually got some calls from our, from our capital and market investors, saying, look, we’re surprised how many of your borrowers you actually know for its hand, you know, you, you, you pretty much know every borrower that you lent to. You haven’t gotten that, but eventually it’s going to have to happen.
Yeah, I mean, we have, we try to maintain that particular approach because it’s, it’s what may goes pretty much unique in the market. And I think a lot of people see value on that and want to keep it as long as possible. But at the same time, we know, you know, for the next chapter and first scale, we’re going to need to replicate ourselves as many diagnosed as we can.
Correct. And that’s where, you know, Romney, Kim, Olympia, all of the key employees that we have have come into the picture. And, you know, those are just like 2.0 for us.
Kevin Kim, Esq.:
You’re, you’re in that recruiting phase of pro level.
Gabriel Sultan:
That’s the hardest part of scaling a business is talent. Miami is not an RTL city. So I mean, finding talent that knows about RTL, lending in Miami, it’s a challenge.
Kevin Kim, Esq.:
Actually, I want you to spend on it real quick. Complete tangent. But like, yes, that is true.
And I only recently understood this. Miami is not a fixed in foot town, not a ground construction town. It’s a condo town.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
Correct. Right. And like for our audience, can you expand on that a little bit?
Because like educate them a little bit on that because you’re really not, like your core borrower is really more of a, like, I’m buying like a investment property, but I’m not going to flip anything. I’m just going to, I’m just buying a condo. Right.
That’s what they’re doing, aren’t they?
Daniel Benarroch:
Oh, cool. That was Florida and especially Miami pre-COVID. You know, after COVID, we had a really market shift in terms of what our core product was.
Obviously, back then, condos was a big thing. You know, the majority of the international buyers were buying condos because it’s pretty much easier for them to maintain. You know, you just close out the door and pay an HOA and you don’t have to take care of anything else.
You know, migration was mainly from Venezuela, Colombia, Argentina, you know, countries that speak our same language. We understood them, their needs, whatever they need. You know, we click very good into that market, but we realized quickly after COVID, you know, we need to start serving a different audience.
Kevin Kim, Esq.:
So inventory started dwindling.
Daniel Benarroch:
Correct. And the migration was from, you know, out of state. It wasn’t from a lot of the country.
So we started looking at a lot of people coming from New York, from Texas, from California, you know, we were getting an influx of people coming here. It was like, look, there’s a need for them to have, you know, good inventory, you know, up to date. So that’s, I mean, I always tell, we were at the right place at the right time.
Gabriel Sultan:
When COVID happened, I don’t remember how much AUM we had in the fund. So we had a meeting back then, Daniel, myself, and our ex-partner. We said, look, our goal is to preserve capital.
We don’t care what happens. We don’t care to originate loans. We just started this and we’re not going to lose the dime of our investors.
And we didn’t know what was about to happen, right? Nobody knew. I actually bought my first home with my wife, like, in the middle of COVID.
And my dad and my family was like, you’re crazy. Nobody buys like, I’m telling you, like when the lockdown happened, I bought my house. Obviously it was a good decision now.
Kevin Kim, Esq.:
Greatest decision.
Gabriel Sultan:
But back then, people were like, why are you doing the world is going to end?
Kevin Kim, Esq.:
So, oh, no, we were, okay, I was California, like, dude, yeah, Texas, California, everyone’s gonna start buying houses. I almost bought a house in Texas.
Gabriel Sultan:
Yeah. So I mean, like, so you know what happened with Florida? I mean, the southeast pretty much the, sorry, the northeast pretty much migrated home to Florida.
And we were in the right place in the right time.
Kevin Kim, Esq.:
Well, I know actually know some shops out there that actually couldn’t transition into RTL correctly. They struggled with it. And then the market had already taken off.
And, you know, they kind of had struggled. Like, what do we find new deals? Because the condo volume is down.
You’re not just, you’re not seeing any more construction in that arena, but there’s still residential deals happening. So I’ve seen it, percent of lenders have struggled trying to find it and combat that.
Gabriel Sultan:
And our company has grown with our client needs and at the same time, a capital needs. So we’ve been like molded into what Alto is nowadays. It’s not 100% what we had envisioned in 2019.
It’s a mix of what the client, the retail client is asking, okay, I want to build ground up. I want to build a condo. I want to build a warehouse.
And then what the capital behind us is saying, okay, I’m comfortable with this. Or even if we’re not pushing that product, okay, you should be pushing this.
Kevin Kim, Esq.:
So these are the open questions you get about the Florida market or any, every time anyone asks me about breaking into Florida, like they have trouble understanding how those shops are structured, because not everyone’s different. How are you guys set up for capital? You partner with an aggregator or with an institution, you mentioned funds, let’s get into that a little bit.
Gabriel Sultan:
We have a balance sheet fund that we have a nice attorney that’s set up for us. It’s not cheap, but he’s good. And then obviously we have our second strategy, which is pretty much working with the situation, asset managers and selling them the credit profiles.
Yeah, and we have multiples of those. And now we’re going to have a third strategy, which is securitizing, which you can argue that it’s a mix of both, right? It’s pretty much a line, a 90% line, but you still have to go and sell it.
Kevin Kim, Esq.:
So I set it up and also you need to have the balance sheet to do it. You have to hold onto that risk.
Daniel Benarroch:
But I think more important that the balance sheet is the knowledge and getting some kind of asset management exposure, because what Wheeler and really quick is, look, if we don’t feel comfortable managing and you don’t be in an asset manager for this, which we indirectly are. I mean, we’re still selling the paper, but you’re still getting most of the work done yourself.
Kevin Kim, Esq.:
This whole servicing thing is like, yes, your loan buyer may require a third party service here, but that’s like the beginning of the story.
Gabriel Sultan:
We do the whole work between you and us. We have a team of like 10 in the servicing department. It’s called shadow servicing, but in all reality, it’s a real service.
Kevin Kim, Esq.:
Yeah, the appointment services really just to keep the institutions happy.
Gabriel Sultan:
Yeah. So yeah, as you said, we work right now with three main capital partners. And one of them has a big, big chunk of our volume.
And I think we have maybe 12 MLPAs open that we’ve signed that we can engage with them, but we’re only interacting with three, because number one, we need to really know who that capital is. And you only know who your capital provider is in bad times. You know, when in the first 12 years, everything is a honeymoon.
Everybody’s happy. The loans are performing. Everything is kumbaya and everyone’s happy.
And then as the relationship grows and the portfolio grows and you start having late payments for closure scenarios. And you see and they see how you as the lender originator, you know, gives them advice, gives them response, gives them access to a virus. And at the same time, how friendly are they to meet, you know, common grounds and find the solution?
That’s where you realize who you want to work with. You know, we are not engaged or selling paper to anybody that’s under the lent to own strategy that doesn’t negotiate, that doesn’t give a guy who had a health disease, a 10 days grace period. We’ve had that issue, we’ve had, you know, sponsors who their spouse died and they’re called, Hey, I didn’t make the payments for 60 days.
Here’s a newspaper, my wife died, I was in the hospital with her, my babies are crying, I’ll pay you tomorrow. And then we call, we explain the situation and they’re like, no, I’m sorry, they’re in default. 24%, no question of task, no, we’re like, we’re not going to work with you.
Kevin Kim, Esq.:
My experience has been the vast majority of the loan purchasing institutional market is very much like that, right? They’re not going to care. It’s all numbers on a spreadsheet to them.
Right. And so they’re very much not interested in getting into those scenarios. And they just kind of, it is what it is default default default.
And also hold you to account. And they’re not going to really negotiate as you’re putting it, right?
Gabriel Sultan:
That’s so. But we explain to all of our capital providers that our goal is to have repeat clientele. We’re targeting guys who do 10 deals a year.
The guys who do two, three years of deal, we’re really not targeting. We’re targeting 10 plus. So for us, it could be one deal, I’m not going to wave any foreclosure.
I’m not going to wave any default fees. But for us, it’s not one deal. It’s 10 every year or 20 or 30 or 50.
So whenever we right now engage with any of them, we tell them, like, look, you have to be reasonable. Like this is people.
Kevin Kim, Esq.:
But you’re also going to reward them with flowing volume. With flowing volume.
Daniel Benarroch:
Yeah, I know. And we’re always going to pick up the phone and try to find a solution. So like we’re going to say a little, you know, I don’t know what happened with the borrower.
We never met her. He came to a broker. Yeah.
Kevin Kim, Esq.:
You know, and there’s an extreme version of that in today’s market. We’re like, and this is just a product of so much capital being out there as many lenders and originators have told me effectively what they’re doing is they’re basically, they have their side with everybody. And they’re treating them purely as a transactional relationship.
And that was actually a smart move post COVID when everyone was scrambling to find a home for a deal. But in today’s market, what I’m hearing from you guys is it’s paid off to have a deeper relationship based kind of partnership with these loan buyers.
Gabriel Sultan:
No, and we look as a company, as individuals, we’re really relationship driven. Obviously our background, we were born in Latin America. Our Latino culture is really warm.
We know our guys. We know their birthdays. We know when their kids are having either quinceaneras or whatever you may want to call.
So we care about them. So for us, for closing on someone who’s trying, it’s sad. I mean, we know the outcome and we know how it could end.
So we really try to avoid it. Obviously in a lot of scenarios, it’s you have to do it. We really strive for customer service and understanding the clients.
And that’s what we tell all of our guys like, look, if you’re not going to make your payments, don’t wait until I call you, Hey, what’s going on? Call me before call me two weeks before and tell me, you know, just tell me, look, I’m not going to be able to pay the next three months. We’ll speak to our investor and we’ll tell them, Hey, this is a strategy.
This is how you’re going to get paid off. Let’s do a deferment agreement. Let’s do something.
And we really try to work it through.
Kevin Kim, Esq.:
Well, that explains why you signed up with 12, but you’re only really working with three. Yeah.
Gabriel Sultan:
Some of them were like full charts.
Kevin Kim, Esq.:
Yeah. Yeah. And we don’t work with that anymore.
It’s been my experience. The vast majority of them are not well, a lot of them aren’t asset managers. They also are reselling those loans and they got to answer somebody or they’re taking those loans.
They’re securitizing. So they have no choice and they have to be cold about it. So I guess it’s also a question of like asking your counterparty, like, what are you doing with my loans?
Because if you’re doing X, then maybe they’re not a right fit. And it sounded like to me, especially in today’s market where everything is so lumpy and so lots of crises happening left and right that maybe that is better to have some of that’s more of a flexible capital partner.
Gabriel Sultan:
So I would give that advice, you know, have many options. You know, diversifying is key, but identify people that you like working with. That’s number one.
And then they’re reasonable and they’re not going to be, you know, they’re not going to hold every T of a contract. And if you present them with a reasonable outcome solution, you’re going to find common ground. Yeah.
You have to find people you can work through. Yeah. And that’s why you said we had 12, but we’re only engaging with three.
So we have nine that they’re calling us.
Kevin Kim, Esq.:
They’re calling us.
Gabriel Sultan:
Please, we need volume.
Kevin Kim, Esq.:
Let’s let’s contrast that now because you have to you guys are going towards securization.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
Right. And it’s a lofty and a great achievement, but it’s also comes with its own consequences. Right.
Like, how are you guys going to erect in style? You know, because the securization, you have no choice. Yeah.
You know, the logo is bad. You got to move out the line. You got 60 days, you have no choice.
Gabriel Sultan:
Look, I’m being honest with you. And we’ve had this discussion many, many times we still haven’t made the decision if securitizing makes sense. Yeah.
But then the other side says everybody’s doing it. Everybody that’s our size and scaling has done it. So it’s natural.
And it’s again, it’s diversifying. It’s a normal strategy.
Daniel Benarroch:
Yeah.
Gabriel Sultan:
But yeah, you have to answer and you are going by the rules or whatever you write in those agreement, those. And if the loan is has been 24 months on the books, there’s no way of getting it.
Kevin Kim, Esq.:
You have to get it off.
Gabriel Sultan:
You have to get it off. So either we keep it on our balance sheet, because we love the entrepreneur who’s behind there. We want to help him or we have to foreclose.
Kevin Kim, Esq.:
That’s a very common struggle we see out there. I mean, you’re not the only one. Yeah.
I mean, for those lenders who’ve done it already, they’re struggling with like, okay, well, the options are now to go rated, unrated. Today’s market, they’re not that far apart anymore in pricing. It’s way more scalable and more affordable to do the unrated right now, considering it’s only 30, 40, 50 basis points, different, not a huge right home.
Daniel Benarroch:
But that’s a really interesting point. That’s being one of our key alerts, it’s concentration issues, because obviously as a local player, I mean, you know the market really well and ineligible for rated. Because you’re just going to go out and like, but you’re concentrating in Florida is a loop.
Yeah.
Kevin Kim, Esq.:
You have to go. I think you guys are going to have to start unrated. But even that, many lenders who are kind of similar, regional lenders, high volume, good quality loans, have struggled saying, this is not for us.
It’s the cost of doing one and the cultural impact is going to have on our business. I don’t know if I want to pay. I don’t know if the economics are worth replacing that.
Gabriel Sultan:
Yeah, it’s true. And it’s the direct and indirect cost, because you also have to hire people just to manage and people that know an expensive talent.
Kevin Kim, Esq.:
You need a lot of quality talent.
Gabriel Sultan:
Yeah. Yeah. So you need to, if you’re going to do one is because you’re just going to keep doing them for a year.
You’re just not going to do one deal.
Kevin Kim, Esq.:
Well, the companies have done a lot of them. A lot of the big institutional clients who have achieved a lot of those kind of, you really, a lot of those notch on the belt, they have a massive team. Yeah.
Right. And they got, they don’t just have general counsel. They have got a lead by the way.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
That was actually my question is like, what’s the team comprised of today?
Gabriel Sultan:
I let you guess for an originator that’s, you know, doing 120 a month, you know, what do you think it’s our aside?
Daniel Benarroch:
Average loan amount.
Kevin Kim, Esq.:
It’s like a million right now.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
Typically 120 a month in volume, average on 100 million plus. Yeah. You’re looking at an, at about 50 to 100 employees.
Roughly. Yeah.
Gabriel Sultan:
So we’re like at 16.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
We’re like 16, 6, 6, 0. Yeah.
Kevin Kim, Esq.:
Okay.
Gabriel Sultan:
Maybe with AI, we can go to 16, but not yet.
Kevin Kim, Esq.:
So six zero, but like, that’s still kind of small.
Gabriel Sultan:
We have in our back office offshore, we have 35. So I guess then 31 here in the States, which is mostly like sales, steam and key people like CFO, COO, marketing people, chief revenue officer, et cetera. And obviously all of the LOs and sales people.
And then everybody else is offshore.
Kevin Kim, Esq.:
That’s still pretty dimly.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
Yeah. And that I would give the advice of trying to find people offshore for the back office because you’ll save. And again, when we started this business, it was really hard finding people offshore that knew about mortgages or anything.
Now you would amaze your, it’s easy.
Kevin Kim, Esq.:
Well, it’s been pretty widely though. Yeah.
Gabriel Sultan:
Even at the top of the echelon, when it comes to the conventional mortgage market, you’re going to find people in Latin America and, you know, Asia that know about what LTV, what an LTC is. And it’s pretty much, yeah, we have, we have people in South America, Europe, and Asia right now. Correct.
Kevin Kim, Esq.:
Yeah. Is your business right now kind of still concentrated in that, like, I would call it the Spanish speaking market or is it kind of broader now? Because your foundation was correct.
Daniel Benarroch:
Yeah. Yeah. Yeah.
Kevin Kim, Esq.:
So obviously we started with those clients that, you know, we still serve and they’re, you know, they’re so famous in Florida, you guys are the number one player for a long time. Yeah.
Gabriel Sultan:
I mean, in our office, I think 75% of the office, like we speak Spanish a lot.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
But again, obviously we service, I mean, we’re in the United States, so we service anybody. But if you find that Latino flipper, entrepreneur, the developer, there’s, and you give him a term sheet from us and you give him a term sheet from a lender, you know, wherever in the Midwest or even in the Bay Area, I think chances are he’s going to relate more to us.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
And he’s going to say, Hey, I have something in common with this guy. Yeah. I can just call him and tell him I’m in my mom’s piñata or whatever and they’re going on their Senate and not call me that day.
So I think that’s an advantage for us that we’ve been expanded.
Kevin Kim, Esq.:
Now you have to find yourself kind of a plane because they’ll grow this. You’re going to have to now go after some of the bigger fish who are doing high volume. They’re institutional in their own right, you know, like on the builder side, like is, has that been a cultural transition for you guys?
Gabriel Sultan:
Yeah, it is.
Daniel Benarroch:
Yeah. Yeah. Yeah.
We have Manuel and Rafa there. So that was our first, well, expedition to Texas. It’s been doing good.
I mean, we’re trying to implement pretty much the same approach and boutique style we had in Miami. So we’re trying to do, you know, small networking events, trying to know the community and from there, start building those foundations for those relationships to flourish. And then Charlotte, obviously, it’s in the right area right now.
And then California, we got our license here. Yeah. Finally.
Thank you. Yeah. So we did that.
That’s one of the works as well.
Kevin Kim, Esq.:
It’s interesting. You say Austin, Texas right now because Texas has taking a beating the past two years. Yeah.
I feel like they bottomed out and they’re kind of on their way up. And with Austin coming out of the ashes, you guys come pick up, I think he was like our second guest or third guest on the show. You guys have hired Romney Navarro, correct?
Yeah. Yeah. And it was just, yeah.
So you call it, you say he’ll makers, but I mean, I’ve known, I’ve known Romney since 2012, going 14, 2014, 15, 15, I’ve known Romney since 2015. And that man is like a mainstay in Austin hard money.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
It weirded me out the other day. I was watching him do a podcast. He was doing it in Spanish, like space, big, big, fluent Spanish always.
I always hold my mind over it, but like it’s a great pickup. And it’s very hard. How did you guys connect?
Gabriel Sultan:
Our CEO used to work for him. So she has sure. Yeah.
Yeah.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
So she’s been since day one, you have to meet Romney. You have to meet Romney.
Kevin Kim, Esq.:
That’s good.
Gabriel Sultan:
At one point of view, bring him and like, okay, who am I meeting?
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
And then we were like, you were right. We had to meet.
Kevin Kim, Esq.:
I love, I love kind of like the old school of the industry, finding their way back into the new school. But also when they, when they mesh so well into organizations, very, very hard to find that because a lot of times, the older generation of lenders, they just can’t, it’s actually a really good point because part of our job with Romney for the last 90 days has been, it’s like, look, you know everything this business before us.
Daniel Benarroch:
But now we have to bring you up to speed what’s been this business the last 10 years. So it’s been an interesting mix there, you know.
Kevin Kim, Esq.:
And Texas has become basically the largest, second largest market in the industry. It became so popular that every institutional and all the top 20 shops land in Texas. And so, and he was, when that started happening, he already kind of walked away from the industry.
So they’ve learned, relearning the space, both from a lending standpoint, but just understanding what the landscape looks like. I mean, it’s completely different market now.
Daniel Benarroch:
Yeah. He was like, I’m coming to a completely different industry. Like, an international loan in Texas has changed dramatically the last 10 years.
Gabriel Sultan:
Yeah, I mean, but at the same time, Texas is different. I mean, you, you have a lot of people doing 100 LTC. So it’s tough, getting capital for that.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
So it’s tough, Texas. But we’re, I mean, it’s, it’s working.
Kevin Kim, Esq.:
It’s working.
Gabriel Sultan:
Yeah. And we’re trying to do the same in California, hopefully.
Kevin Kim, Esq.:
I think California actually is a bit, a bit safer. And frankly, it’s just not as oversupplied as Texas says.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
We have way more regulation.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
And it sucks in that respect. And don’t even start off for closing here. But, but at the same time, I mean, it’s faster than in Florida.
Gabriel Sultan:
I mean, even or not.
Kevin Kim, Esq.:
Well, we have the same time. Stupid SB 1079 thing. So like, technically, it’s faster, but you’re waiting online until someone can scoop you up.
Right. So that thing sucks. It’s a, it’s a, it’s a, it’s a, it’s the landscape ball of fraudsters.
But at the same time, we don’t have inventory. We have, we have an inventory problem here. Texas had an oversupply problem.
Correct. So like, that still keeps values, at least remarkably.
Gabriel Sultan:
You know, and you hit something about foreclosures. And that’s a question that I have for you. Yeah.
When we started capital, their, their buy rates used to be different on the Geos, right? Yeah. And you would have a discount for, you know, Texas, Georgia, Arizona, the, the states where you could foreclose in a week or a month or two months.
Now when we see our pricing, and it’s pretty much the same in every deal, we’re like, look, you should, you guys have to put, you know, if you do a loan in New York at nine, and then you do a loan in Georgia or Arizona that are super fast for closing, it should be at seven.
Kevin Kim, Esq.:
My understanding is, yes, that is true. But one, one, the one nuance we did discover over the years is that there are certain pockets that are judicial states. And this is the one I always talk about.
It’s Massachusetts, a good example, right? They are a judicial state. But for commercial transactions, which we were doing, it’s expedited.
So you’re faster, you’re actually faster than you are. Not Texas. Texas, you’re done in 30 days.
Daniel Benarroch:
Yeah. That Texas is laying on your golf. Jordan, Jordan, Arizona, you’re out.
The Georgia has been one of the fastest.
Kevin Kim, Esq.:
Yeah, we have for a quarter. And Georgia is kind of a hybrid judicial, non-judicial state. Okay.
Right. But these are states that have remarkably understood the difference between commercial and non-commercial. Florida has decided that, hey, if it’s residential, it’s residential, it’s residential, right?
We don’t care. And that’s what a lot of the problems lies. So it’s not necessarily judicial versus non-judicial.
You’ll see non-judicial states that have all kinds of wonderful protections on it. California is a good example, right? So California, yes, yes, technically, non-judicial, you’re out 90 days, but you have to wait, right?
Because SB1079 says it’s one to one to four family, you have to wait during that rescission period for non-profit to be able to buy that thing. And they’re reworking the law right now. But it sucks because you think you’re in credit bid, you’re going to get the property back, you could value, but someone can come in and scoop it out from underneath you.
And so that creates massive delays. And then also because you have the regulated market, you have very smart borrowers, which throw massive delays into the foreclosure process.
Gabriel Sultan:
And so there’s more than they have good attorneys.
Kevin Kim, Esq.:
Yeah, that too. I mean, a lot of the BK attorneys are just really, really opportunistic, and they’ll throw, I call it strategic BK, and they’ll just make sure that as a lender, just throw you off your game and make you spend through the nose, and basically it’s not worth it anymore, right? And it’s a pretty common tactic.
You’ll see that. And it’s not necessarily that it’s not as nuanced, as simple as judicial, non-judicial. Look at the local for color timelines.
And so that’s one of the things I get nervous about when I see a lot of lenders use a national foreclosure trustee. You kind of want to have local intel. You want to have a local specialist, in California, I tell people, you kind of want a foreclosure guy that’s really good in that Bay area, right?
And then you want someone who’s really good here, you don’t want because they’re two different countries. Yeah, it makes sense. Yeah.
And especially like, or even Orange County to LA, two totally different countries. So you got to think like that, and that saved a lot of heartache from a lot of clients. But capital markets, I think it’s a matter of like, they want.
I don’t think it’s a question of like risk. I think right now they’re looking at it like, we love this.
Gabriel Sultan:
Yeah. No, we’ve seen it. I mean, the amount of capital out there is just, it’s crazy.
And that’s, as we started, you know, getting to the business and started going to New York’s two meetings, we went to a meeting in New York, you know, our first meeting in New York building, you know, we went to a 50th floor, Central Park. And that’s one of the points that we say, oh, we’re real.
Gabriel Sultan:
Yeah.
Gabriel Sultan:
And then you start hearing billions and billions and two billion, three billion, a billion here. And I’m like, they’re like, what is happening? Like, where are we?
Kevin Kim, Esq.:
You know, I still remember my first meeting with, with Nomura at like a big institutional event. And I was like, they’re just talking about like, what’s the minimum production? You see, this is back then.
This is about seven years ago. And they’re like, Oh, minimum production. Yeah, about 150 million.
I’m like, no one does that back then, right? But now they do. But back then, no one does that.
And it was one of those fascinating conversations, like where we are today. Capital wise, as you said, though, I mean, I don’t know how you guys, if you guys are getting these, I’m getting these where it’s like someone that I thought had written this stuff off, had said no to me outright. We’re never going to do that stuff or not buying.
Gabriel Sultan:
Yeah, it’s true.
Kevin Kim, Esq.:
Or have bought into a company or have done this and that.
Daniel Benarroch:
Yeah, I think we’ve been to a few cycles already to understand, you know, when the capital opened the floodgates, as we call it, and then we start, you know, constraining and closing a little bit. So yeah, we’ve seen obviously the volume right now, it’s picking up. Obviously, main concern for us, it’s when we start chasing loans.
And that’s really when we’d ever say, you know, stop. If everybody wants to do this loan, let them do it. But I think for us, it’s not a good business.
It doesn’t make sense. Let them go to another shop. But I think at some point, you know, we’ve seen the market shifting into maybe like chasing a bit of the loans, which obviously it’s not ideal.
Kevin Kim, Esq.:
I mean, for my purchase, it’s been about three years of that.
Daniel Benarroch:
Yeah.
Kevin Kim, Esq.:
Like here in California, it’s so cutthroat. People do anything to acquire a customer.
Daniel Benarroch:
And yeah, one of the things when we started, obviously, we were making most of our production in points. Yeah. And we seen points shrinking and constraining like 50% of what we were charging now.
Kevin Kim, Esq.:
It was a two on average for you guys.
Daniel Benarroch:
We started a two and obviously we started a three and we, you know, stabilized like a one and a half. Yeah.
Gabriel Sultan:
Yeah.
Daniel Benarroch:
It’s so competitive right now, which is where the compressions happen. Right.
Gabriel Sultan:
And especially in the last, I would say, 12 months, a lot of the big California shops, you know, Genesis or anchor.
Kevin Kim, Esq.:
Every major shop here has a footprint in Florida.
Gabriel Sultan:
Yeah. That’s why we want to come here.
Daniel Benarroch:
No, you should. But the good thing about it is we were so close with our borrowers that obviously right now, you know, on the metrics Forecasa, you can get that pretty much access to anybody. We’re just getting screenshots of their calls or emails.
Like, you know, this is what they’re offering. This guy won’t stop calling me. So I think that speaks for itself, you know, what we build with these borrowers.
Now, we actually, I don’t know if we spoke about it, we felt it was something like giving back to them. You know, we would trust us with your landing leads for the past seven years. Now it’s our turn to say, you know, we trust you here.
It’s some equity for your project. So we started doing that last year. I think we had five projects already funded.
Cool. So yeah, I think that’s a way of giving back and, you know, making that long-term relationship and telling your boring, you know, I trust you as much as you trust me. That’s invaluable to them.
Yeah. That’s how it shows.
Kevin Kim, Esq.:
Yeah. Yeah.
Daniel Benarroch:
I think there’s many people that don’t have any one of those.
Gabriel Sultan:
No, and hopefully we can scale it and also open it up to our investors.
Daniel Benarroch:
Yeah.
Gabriel Sultan:
They may want higher returns and we’re going to get them on the other side.
Daniel Benarroch:
That’s more conversation too. The best thing you can look for, it’s like a really good operator. I mean, that’s the hardest piece of the puzzle.
Kevin Kim, Esq.:
I mean, especially in the syndicator developer market. Like, I represent those guys too, and they’re getting their assets.
Daniel Benarroch:
Yeah.
Kevin Kim, Esq.:
Yeah.
Daniel Benarroch:
Whenever you find a borrower that knows how to execute and repeat that over and over, that’s a one making way of the storm. Yeah. One of the things we saw during COVID is we everybody entered the market, small flippers, small developers on the ground of construction side.
Everybody was doing good. And even if there were no do we know good, appreciation was helping them, right? Yeah.
Gabriel Sultan:
Yeah.
Daniel Benarroch:
And then that faded away. So we saw all of those small players move on to the side and we really saw the true borrowers that were like prepared and were ready to do this for the long term. And, you know, those are the people that we have identified and say, you know, no matter what, we still need to find a way to help these people.
Gabriel Sultan:
I mean, we’ll roll up our sleeves, but we also talk to them and sometimes we close loans in two hours.
Gabriel Sultan:
Right. Right.
Gabriel Sultan:
So we do things the extra mile for them. And we also tell them, like, look, you have my number. Try to do a loan with anchor and caller CEO or try to call the CEO over or genesis.
I mean, you’re not going to get, I mean, you also have to value that, right?
Kevin Kim, Esq.:
So this is funny because I hear this a lot of like, service pricing, right? And a lot of interviews, it seems almost like it’s a binary conversation. You can’t have one without the other.
You have to have one, not the other.
Gabriel Sultan:
No, you need to be competitive, no matter what.
Kevin Kim, Esq.:
That’s the thing, right? So that what everyone’s been saying is like, a lot of folks have been saying that we kick ass on service, but we just can’t compete on price, right? But you guys are trying to, you guys seem like you’ve solved it for both or somewhat, right?
Gabriel Sultan:
It was work in progress, but we also land them to her feet and saying, hey, you’re doing a $3 million deal. $5,000 is not going to kill the P and L or the profit of the deal. If I’m $5,000 more expensive, but I’m giving you service access and you know me, just come.
I mean, there’s no reason for $5,000 to go and try something new. In Spanish, there’s a really good saying that it’s better something bad that you know to something good that you don’t know. It’s in the translation.
It’s not that the goal.
Kevin Kim, Esq.:
The goal that you know kind of thing. Exactly.
Daniel Benarroch:
And did you know what you’re dealing with?
Kevin Kim, Esq.:
Exactly. Yeah, yeah, yeah, yeah, yeah.
Gabriel Sultan:
Exactly.
Kevin Kim, Esq.:
But you’re also making it easier on them, right?
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
It stings a little bit now, $5,000, but you understand what you’re getting for that $5,000, right?
Daniel Benarroch:
Comparatively speaking. No, we’re still super competitive in pricing. I think we haven’t been beaten by any quotes in the last 18 months, right?
Kevin Kim, Esq.:
So a lot of folks are trying to win their inability to compete on the same side.
Daniel Benarroch:
You have to understand they have different economics that we have, you know.
Gabriel Sultan:
A friend of ours, he started an RTL shop eight months ago.
Daniel Benarroch:
Yeah, less than a year.
Gabriel Sultan:
He came from the world because he managed our pool of money and they invested a ton of money into a multifamily lender and they went south. So he opened an RTL shop and he came to us two weeks ago and he said, I’m done. Like I’m not doing any more RTL.
It’s too competitive. You guys are charging a point or 75 basis points. If you’re not doing over $100 million every month, it’s just not worth it.
So I rather, he says, I have a substantial amount of AUM. He said that he had raised $100 million. I’ll do deals that are not down the fairway.
You know, I’ll do a warehouse. I’ll do a medical building. I’ll do, you know, not RTL stock commercial commercial.
Yeah, you can chase it. I want 12 plus two. Just call me when you have one of those.
So that’s something we’ve, it’s the first time that somebody has said, look, this is, it’s not really a market for a new entrant, like for a market.
Daniel Benarroch:
Yeah. Well, that’s a really good point. When we entered the market, it was, they still had some space for a big lender.
But I think right now it’s, it’s super hard, you know, a little bit of barrier of interest.
Gabriel Sultan:
Especially in the southeast.
Daniel Benarroch:
Top market in the southeast. I mean, but you know why it’s market shade, market share wise, capital wise is easier. Back then on 2019 to find the capital was hard.
I mean, we didn’t even knew that table funding was a possibility. And there were not shops that were advertising and, you know, they didn’t have any business development guys calling everybody to see, you know, do you want a table of fund deals?
Kevin Kim, Esq.:
Well, also, it was a different access to the Intel. So the market markets guys are so happy that all this Intel is out there now.
Daniel Benarroch:
Yeah, but capital was hard to find. I remember those times where we used to know and Toorak and all of the big institutions, like look, you’re too small for us. You know, you need to be doing that.
Kevin Kim, Esq.:
You guys try to jump in when they were now at a certain point where they had to be more picky.
Daniel Benarroch:
Yeah.
Kevin Kim, Esq.:
Right. At the beginning.
Daniel Benarroch:
Yeah.
Kevin Kim, Esq.:
At the beginning, they were right. Right.
Gabriel Sultan:
Right.
Kevin Kim, Esq.:
Right. And it was kind of running joke. It’s like they’re basically buying from everybody and anybody until like, it was almost like 2016, 2014 to 2018 was like, they were just buying, like peer should be buying for everybody.
They could get their hands on because they want a market share. Right. But then they had to realize, hey, we kind of need some discipline to this, Toorak the same way.
And I mean, all those guys have kind of, you know, but the capital above them is not coming down.
Gabriel Sultan:
Yeah. Yeah.
Kevin Kim, Esq.:
So that’s the, that’s the scary part. It’s like, wow, there’s a real appetite.
Gabriel Sultan:
Yeah. They’re cutting the middlemen as we know. Oh, yeah.
Kevin Kim, Esq.:
Right. And they’re better at it too. That’s the fascinating because they don’t, they don’t have to deal with the interaction, middle, intermediate, intermediate economics anymore.
Gabriel Sultan:
Yeah. And they’re buying so much of the, they say, look, we just need a team of whatever 10, 15 people to manage this and we’ll do it in house.
Kevin Kim, Esq.:
The fascinating part is a lot of them also own lenders, which I always am still like trying to reconcile, like, how is it that you’re doing this? I guess you also own a lender. Yeah.
But you’re also buying, but then you realize that, wait a minute, it’s all feet up to this giant pool of assets that tries trying to manage. Right. So yeah, it doesn’t look to be a difference, loans, loans, loans to them.
Daniel Benarroch:
But what we’re seeing right now on the market, which has been kind of new lately, it’s that we, there’s a lot of competitors that are table funding deals. Then there are small shops, maybe three, four, five employees. And obviously their operational cost is way less than we need.
The issue we’ve been seeing, it’s a lot of the borrowers that we say, you know, we charge a point and a half and they went with them because they charge one. It’s, you know, they’ll call you a few months later, say, look, I’m having issues with the draw. They don’t have a draw team set off.
So I don’t know what to do. I’m dealing with some guy in California, you know, or here or there. Maybe you were worth those 25 basis points more.
Kevin Kim, Esq.:
Yeah.
Daniel Benarroch:
Look, we had to maintain operation that, you know, it’s 60, 65 employees. Obviously there’s costs behind this structure to be able to provide the level of service we need.
Gabriel Sultan:
No, and that’s how you have to like forecast your expenses as the growth goes. Like, look, we would have anywhere from 20 to 40, you know, extensions or renews every month. Right now we’re at 100.
So that team increased from one to five, just doing the extension, making sure the capital is there, you know, verifying the taxes, getting the extension agreement signed, it’s a process. So, so the guys who are right now doing a lot of volume, but are not charging enough, then in two years, they’re going to say, how am I going to deal with this?
Daniel Benarroch:
You know, how much we may going to do in each extension, right? No. Zero.
You’re not charging anything on extensions. Zero depends.
Gabriel Sultan:
We want to.
Daniel Benarroch:
I mean, it’s a survey. I mean, look, when you’re doing an extension, because probably somebody’s not doing good or the property sitting on the market, you know, and they’re not willing to pay a ton of money for extending three, six months. You know, we’re just trying to provide a survey.
So I can look, you know, here’s three, six months.
Kevin Kim, Esq.:
That raises an interesting question. That could be solved with DSCR, but you guys don’t do a lot of DSCR.
Gabriel Sultan:
Well, that’s one of our main goals of this year.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
It’s to formally launch our DSCR platform and program.
Kevin Kim, Esq.:
It’s a hard thing to build.
Gabriel Sultan:
Yeah. It’s going to start, you know, God willing on the first of October soon. So we already hired the head over the SCR department.
He comes from the industry. He’s been with us for 90 days already. So we already have capital.
We already have the processes. And you know, we just did a test. We’re doing over a billion dollars a year.
Last year, 35% of that pool was refinanced with a DSCR. So we’re saying, look, if we could just close at least half of it, that’s 200 million.
Daniel Benarroch:
Yeah, I mean, it’s a sort of tool edge, as I call it, because when you’re doing a DSCR and you have a borrower with a fixed and flip loan that it’s mature and you send him to a DSCR refinance, it’s like, yeah, you’re doing the refinance while one pick the extension. It’s like, no, no, it doesn’t work. Like, I think you still have to pay the extension because, you know, this loan, it’s already in another pocket.
It’s not on my balance sheet.
Kevin Kim, Esq.:
We can’t, you can’t be in the fault. If you want to fulfill what it’s hard for the borrowers to understand that, you know, you have to see the streamer into that as lenders will actually like fix the loan with the borrower so it can actually get refied out. And yeah, because DSCR was so popular last year and it was continued to be very popular.
Daniel Benarroch:
Florida has an issue, which is insurance, which is super expensive. Oh, yeah.
Kevin Kim, Esq.:
Obviously we have fires. Oh, yeah, yeah, yeah. At least your insurance companies didn’t leave the state.
No, they left.
Gabriel Sultan:
The Tri-County, the Tri-County date, Broward Palm Beach, most of them left because there was a lot of fraud. I mean, if you’re in Florida and you’re driving on the highway, you’ll just see billboards of attorneys saying, file a claim, call me, call me the doctors.
Kevin Kim, Esq.:
Against their insurance companies?
Gabriel Sultan:
Yeah. And a lot of people, you don’t have a $2,000 damage and they get a check for $100,000. So yeah.
Kevin Kim, Esq.:
Well, we have the opposite problem. The insurance companies didn’t couldn’t raise rates. The government wouldn’t let them raise rates when they left.
Yeah, yeah, yeah, yeah. And you also have fires. Yeah.
Yeah. Makes sense. Yeah.
Gabriel Sultan:
Oh, we have hurricanes. Yeah.
Kevin Kim, Esq.:
Yeah. I think we have one more though. We have earthquakes.
Gabriel Sultan:
Yeah, yeah, yeah, yeah. By the way, we were doing a loan and we were using your docs, Lightning Docs. And the attorney for the borrower calls me like, why do you have an earthquake insurance clause in there?
I’m like, I don’t know. We’re in Florida. And then for sure, it was included like in the Lightning Docs, you know, person.
Kevin Kim, Esq.:
Yeah, yeah, yeah, yeah.
Gabriel Sultan:
We have to cover everything. I’m like, sign it. There’s no earthquake in Florida.
What do you care, right? Don’t even bring it up.
Kevin Kim, Esq.:
There was an earthquake somewhere in the northeast though recently.
Gabriel Sultan:
Yeah. North Florida.
Kevin Kim, Esq.:
Not in Florida. I don’t think it’s possible in Florida. It’s a giant swamp.
Gabriel Sultan:
Yeah. It would be interesting, but.
Kevin Kim, Esq.:
I mean, so you guys talking about building and adding new things, DSCR, one of them. So like, you know, going, we have a few months left in the year, you know, summers here, we’re almost out of it. And, you know, having the big, big last push, Q4 is like right around the corner.
So what’s the horizon look like going in the end of the year? But like, what’s the goal for going into next year, right? 2027.
Daniel Benarroch:
Yeah. So this year goal was to hit a billion dollars, which we achieved pretty early. Yeah, 120 a month.
Kevin Kim, Esq.:
No problem. Yeah.
Daniel Benarroch:
So, you know, second KPI was, you know, let’s try to do 1.2, which is kind of the average we’ve been doing. And I think for next year, I mean, we’re pretty ambitious. But, you know, if we add DSCR and we say, you know, at least we can convert 30% of our production into DSCR loans, I think we should be looking anywhere between 1.6 to 1.8. So something, you know, it takes a lot of effort. And we tell, I mean, one of the mantras, we tell each other, it’s look, we’re as good as our last month, because that’s a reality.
Kevin Kim, Esq.:
That’s real.
Daniel Benarroch:
Whatever you need, that’s amazing. But, you know, John, you know, the first of the month, it’s a complete restore. You have to start from zero.
Kevin Kim, Esq.:
You’re in a service business. At the end of the day, it’s as good as your last month as well.
Gabriel Sultan:
Yeah, unfortunately.
Kevin Kim, Esq.:
Unfortunately, yeah.
Gabriel Sultan:
Like we start all over. I always tell him in new years, I’m all happy in new year. And I’m like, oh my God, we have to do it again.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
The pressure starts again, a new year.
Kevin Kim, Esq.:
My wife is, no, like, I get so cranky at the end of the year, because I have to do this all over again.
Gabriel Sultan:
And look, we’ve been lucky. Every year we do more than last year. That’s great.
We started, like, exponentially. The first year, I think we did 20 million. Then we went to 100.
Then we did, like, 250. Then we did 400. Then we did seven.
Then we did 920. And this year, we’re going to do, like, 1.3, 1.4. Like, every year we’ve grown so much that every first of, the first of January of every year, I’m like, oh my God. Here we go.
Kevin Kim, Esq.:
Here we go again. But it’s scary, too, because you have to build the business expectations or highs, obviously, you can’t drop the ball. Use our service-oriented players.
So hands-on with your borrowers and your capital.
Gabriel Sultan:
I mean, again, we’ve been lucky that we’re in Florida, I say it in the southeast. And now we’re growing to other markets. I do think that next year, you know, 2027 rates should be better than this year.
Again, nobody has the crystal ball. But if you would ask me, I think it’s going to be better. You know, obviously nobody can control what’s going to happen in Iran or whatever happens, but hopefully, you know, rates go down, DSCR starts cranking up again, and our guys are selling quicker. And I think that’s, you know, that’s going to help drive our volume. Right now, we are, you know, focusing a lot on the higher-end product. In Florida, the luxury stuff is selling.
Kevin Kim, Esq.:
Yeah. I mean, it’s here, too. Yeah.
Gabriel Sultan:
So, you know, the game?
Kevin Kim, Esq.:
Anything above 2 million is selling fast. Well, 2 million doesn’t sit on market a long time.
Daniel Benarroch:
I mean, say, how do you see the market? It’s like, look, it depends who I’m speaking with. If I call my borrower in Central Florida, it’s like, this has been the greatest year ever.
I mean, everything I put on the market, it’s selling, like, in two, three days. Yeah, but what’s the home price? I was like, I was like, three, four, five.
No, no, they’re selling a million, you know, like, hundred.
Gabriel Sultan:
No, but he’s a super good borrower.
Daniel Benarroch:
Yeah. But he’s like one of the top fears. But for him, this has been like 2026, has been like the best year ever.
And then we speak another borrower, as you say, you know, it’s been one of the wars here, you know, we’ve been struggling. But what we identified, you know, the ultra high-end luxury market in Florida, it’s really, really what’s right now, like the cheer on top. Everybody wants those houses, every developer, it’s after those pieces of land.
We’re obviously catering and trying to serve that niche that’s there. That’s the same thing in California.
Gabriel Sultan:
When we started, as he said, our biggest one was at 1.5. Right now we’re going up to 10 million on a single unit.
Kevin Kim, Esq.:
So, you know, I used to be so shocked at the number. And now it’s kind of gone.
Gabriel Sultan:
Yeah, that’s all right. Exactly.
Kevin Kim, Esq.:
It’s one more. Exactly. I still remember in 2017, someone asked me to find them a lender that could do a 10 million dollar residential loan.
I was like, wow, okay, good luck.
Gabriel Sultan:
I mean, there’s firms that would do it. It’s not really easy, I’m going to say it, but it’s achievable.
Daniel Benarroch:
But that’s really important. When you have those relationships on the second-door market, with your capital partners, you know, those conversations coming to play. Yeah, you can ask them now.
You have to develop those.
Gabriel Sultan:
Yeah.
Daniel Benarroch:
And it’s, you know, you won’t ask for it out on your first deal. But if they saw a borrower, you know, growing, they started doing two, three, four, five million dollar houses. And now the guy is trying to do a seven, eight million dollar house.
And you brought them there with those track records. You can know us and say, here’s an exception. Can we do a loan for this guy for like 10?
Gabriel Sultan:
And it’s also a quid pro quo. You negotiate with them like, look, if you want the bread and butter, if you want the creme de la creme, the 500,000 dollar fixed-in-flip, you know, light rehab, we’ll give you that. But you also need to give me access to a 10 million lower ground on board 15, you know?
Which makes sense. Yeah.
Kevin Kim, Esq.:
It wasn’t like that.
Gabriel Sultan:
Because again, we have, we have capital partners or providers. They’re saying, okay, I only want to buy light rehab fixed-in-flip. But I’m like, that doesn’t work for us.
Kevin Kim, Esq.:
Well, good luck fighting in the audience. I mean, yeah.
Gabriel Sultan:
We have that, but you need to buy everything that we do. You need like a, if it’s a cake, you need a piece of a whole thing.
Kevin Kim, Esq.:
You’re not incentivized to give it to them because they’re not flexible. Yeah, we have what we need to serve and you always need.
Gabriel Sultan:
Then I wouldn’t need to give the other guy just ground up, a luxury ground up.
Kevin Kim, Esq.:
You find that the capital providers are now having to be forced to be more, I guess you can call it, accommodating to their counterpart.
Gabriel Sultan:
Yeah, 100%.
Kevin Kim, Esq.:
That market is also very saturated.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
So many buyers.
Gabriel Sultan:
Especially with guys that have volume, and I am going to say volume is anything north of 60 a month? Yeah.
Kevin Kim, Esq.:
It’s all right.
Gabriel Sultan:
Then before the conversation was the opposite, like we would call them, hey, I want to sell you this, help me sell it faster. And now it’s pretty much the opposite.
Kevin Kim, Esq.:
They want your business.
Gabriel Sultan:
I want more. What can I do to get more?
Kevin Kim, Esq.:
Yeah, exactly.
Gabriel Sultan:
We’ll cater you and we’ll wind and die. And they’re whining and dining us, you know?
Kevin Kim, Esq.:
That’s what they know.
Gabriel Sultan:
Good to be you.
Kevin Kim, Esq.:
That’s good to be you. And good to be in that position though. But I would imagine that the key thing there is that it has to be a give and take.
You have to be flexible.
Gabriel Sultan:
Yeah. Yeah. My risk is, no, because we do get calls and they have amazing rates.
But we only want loans up to 500,000.
Kevin Kim, Esq.:
It’s not going to work.
Gabriel Sultan:
It’s not going to work.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
Especially for our. Even if rates are amazing, it won’t work.
Kevin Kim, Esq.:
How about from like a, I actually call it recruiting at 60 people to get to 1.2, 1.4, 0.6. That’s 60 ain’t going to cut it, man. How are you guys going to fill the bucket when it comes to employee offices to offices to office space?
Gabriel Sultan:
So we moved last year. We’re moving again this year because, you know, we all grew. We’re on a parking spot, I believe it or not.
I always get to my office and I say, there’s more cars than people. You know, yeah, I don’t know. But we’re always hiring people.
And now we’re like forecasting, like we know by every 300 loans, we need, I think, in the servicing payoff closing, whatever, two more heads offshore. And all the same goes with our draw department. Like I think it’s every 100 or 150 more loans active.
We need one more person. So we’re like constantly hiring. And then obviously the DSCR are more on the riders.
Kevin Kim, Esq.:
Way more complex on the running there.
Gabriel Sultan:
Yeah.
Kevin Kim, Esq.:
Yeah.
Gabriel Sultan:
But it’s a constant pain hiring people. Again, talent is, it’s hard to find especially in South Florida and it’s not cheap. And that’s what you see.
Like if you, if you go upstream and you see Blackstone, KKR, Brookfield, they just have the best talent and they’re not cheap about it. And that’s a switch that you as a business owner make at some point. Or in the beginning, you’re saying, oh, I just want to hire cheap.
I just want to, you know, and then you’re saying, no, I need to pay. And I don’t mind paying, but I want to get the right people and I want to get the right people.
Kevin Kim, Esq.:
There’s the right price point and you’re paying for quality, but quality is quality with certain aspects. But you also need fit and fit can kill a business.
Daniel Benarroch:
Yeah. We call it people that help you do your work versus people that do their work.
Kevin Kim, Esq.:
So that’s the right way we put it.
Daniel Benarroch:
You know, you can find somebody that helps you do some things you need to be working on. And then you can find somebody that’s going to pretty much excel at the company and really lift up and say, you know, one for those one, it’s more than two.
Gabriel Sultan:
And we’re a bit different when we hire and, you know, we have our CEO, she’s from Texas, she’s not a Latina. So sometimes in the interviews, I ask questions and after she’s like, that’s not appropriate. I’m like, how many kids in the first interview?
I’m like, how many kids you have, you have friends?
Kevin Kim, Esq.: You can’t say that.
Gabriel Sultan:
What do you do in Miami?
What do you do in the winter?
Kevin Kim, Esq.:
I want you to know, as your attorney. I’m telling you, you can’t say that.
Daniel Benarroch:
Well, I’m just trying to get to know you personally.
Gabriel Sultan:
I want to make sure that, you know, I’m dealing with somebody who’s a normal person.
Kevin Kim, Esq.:
Right, right, right, right. Yeah, there’s laws against that now.
Gabriel Sultan:
And look, we’ve learned that in business. We, you know, the reason why we change from equity lending to auto, we had a partner and things didn’t work out with him. So we had to rebrand because we pretty much bought him out.
And the first thing in a partnership is you need to generally like the person. No, yeah. You end up spending, I spend more time with him than I spend with my wife.
Oh, yeah. I mean, you know, that they has 24 hours. You sleep six to eight.
You’re in the office.
Kevin Kim, Esq.:
But that’s a partnership that works though, right? Because you see that all the time where you partners don’t see each other. And there’s dysfunction in the business.
Gabriel Sultan:
But when my friends come for advice and they’re like, oh, I want to partner with this guy. I’m like, look, don’t even start thinking if he knows the subject, if he’s smart.
Gabriel Sultan:
Yeah.
Gabriel Sultan:
Look at the guy from a social aspect.
Gabriel Sultan:
Yeah.
Gabriel Sultan:
Does he have friends? Does he have a wife, kids? All of those simple questions and you’re going to see who that person is.
Kevin Kim, Esq.:
I found the hardest part is to find a good fit. But once you find that good fit, you’d never let the person go.
Gabriel Sultan:
Well, we have one employee who you know that he told us that he drew, he drove his grandma, the van into a lake because he wanted to learn insurance. If you know what I’m talking about, I’m not going to say names. And I was like, oh, this may be too much.
Kevin Kim, Esq.:
He was young and stupid.
Gabriel Sultan:
Yeah, it’s fine.
Kevin Kim, Esq.:
It’s fine. All right. Well, before we close out the interview, I do want to ask you guys, where can our audience find you guys?
I mean, clearly you guys are recruiting. That’s important audience to know. You’re also growing so that if they want to send some deals your way, where can they find you guys?
Gabriel Sultan:
I mean, you can find those in Miami. You can find those in Texas. And our emails are super easy.
I’m Gabriel@altocapital.com and Daniel is just Daniel@altocapital.com. And we’re super hands-on. I mean, just when we started the business, we started him, Daniel, myself, and another person.
And we were doing draws. We were doing servicing. So we know how to do pretty much all of the processes in our SOP from A to Z.
So when a client calls us and he’s like, look, I need to pay up now. And I see that our servicing team is like not performing. We’ll literally just some get up and we’ll start doing it in their computer.
Or the same goes with draws. So and the same goes to our clients. Like we don’t discriminate by deal size.
If somebody calls us for a 200,000 dollar deal or a 30 million dollar deal, they’ll get the same treatment. And, you know, and we’re open for business. We’re growing.
We’re looking to expand to bring people or culture fit with us. And, you know, California is one of the markets that we feel that we could target now and maybe get some of those Latino Hispanic clients here. We don’t know if there’s another Hispanic Latino lender in California.
Kevin Kim, Esq.:
They’re a couple, but they’re kind of their pocket markets. So we’re better. Old tribe.
The boys from Miami are here.
Gabriel Sultan:
Exactly. So we’ll try to bring the Florida flavors here.
Daniel Benarroch:
Yeah, I love it. And they’re also out of the golfers, so.
Gabriel Sultan:
Yeah.
Daniel Benarroch:
And actually important to mention. We started last year, an event that’s called Alto Circle. Our second edition is going to be October 29 in Miami.
So if you’re going to be around, you’re more than welcome to them. But the pretty much was our away from us to give back to our community, which was pretty much a night where we bring everybody that’s on our circle. Either that it’s insurance guy, brokers, wholesalers, investors, obviously our borrowers, appraisers, title companies.
So pretty much everybody that we touch on a daily basis, we bring them up. And we actually do a really interesting relationship again, where everybody will use a batch and it will tell pretty much with a color, what pocket you’re fitting is you’re like a GC, a borrower, whatever. So there’s a guy that goes around and says, whoever needs a GC, he’s your guy.
Gabriel Sultan:
That’s cool.
Daniel Benarroch:
So we’re pretty much trying to connect each other right now and create relationships, which it promotes the base and what we stand for. Yeah. This won’t be our second edition.
It will have a special celebration. It’s a dating mixer. This one will have a special celebration because we reach 3 billion since the inception.
Gabriel Sultan:
Maybe in October we’ll be at four.
Daniel Benarroch:
Maybe, yeah. Maybe in October we’ll be at four. So we’re going to do it as a celebration as well, so everybody will be more than invited.
It’s going to be at the manna.
Gabriel Sultan:
They will fly you down to Miami.
Daniel Benarroch:
That’s a big deal.
Gabriel Sultan:
Even considering the expensive party, he gave you like a sweet, nice speech, but it’s really a party.
Kevin Kim, Esq.:
It’s a shitty, that’s how amazing achievement. Because those big B markers are hard to hit and people underestimate how much work goes into it. That’s a lot of loans behind.
That’s a lot of loans. And phone calls.
Daniel Benarroch:
And phone calls. Most important thing for us, really, behind every loan, there’s a person. And I think that’s what this tinglish report, I mean, you can ask me about any address, any loans that had any issues, but I always remember the guy who started doing one or two flips with half or 70% of his savings.
And right now he’s a very successful entrepreneur. The guy has been 30, 40 flips already into his belt. So that’s really what made you proud.
And I said, I was able to help you into that dream. And that’s really what brings proud to the organization.
Kevin Kim, Esq.:
And this event is happening in October. All right, so far, listeners, if you’re local to Miami, check it out. All right, guys.
And that’s all the time we have for this episode. Guys, thank you so much for sharing.
Daniel Benarroch:
Thank you so much. Thank you for having me.
Kevin Kim, Esq.:
We’re here at the conference. We’re going to have a great time. Thank you for listening to this episode of Lender Lounge with yours truly, Kevin Kim.
We will see you on the next one. This is Kevin Kim. Signing off.
Subscribe to Lender Lounge on your favorite podcast platform. And visit our website, fortralaw.com to learn more about how we can help you scale.